


How to qualify for tax residency (60/90-day rules)
Day counting is not only defensive. If you are establishing a tax home — for a favorable regime, a residency certificate, or treaty protection — you need to reach a threshold, and prove it. Bounded counts in that direction too.
The qualifying counters
- Cyprus 60-day rule — tax residency with just 60 Cyprus days, provided you are not resident elsewhere and keep local ties.
- UAE tax residency — the 90-day and 183-day routes, both covered.
- Portugal NHR — the residency count underpinning the NHR regime.
- Puerto Rico Act 60 — the presence test for the US territory’s incentives.
- Become Tax Resident — the generic version: any country, any threshold, counting up.
How 'reach at least' counters behave
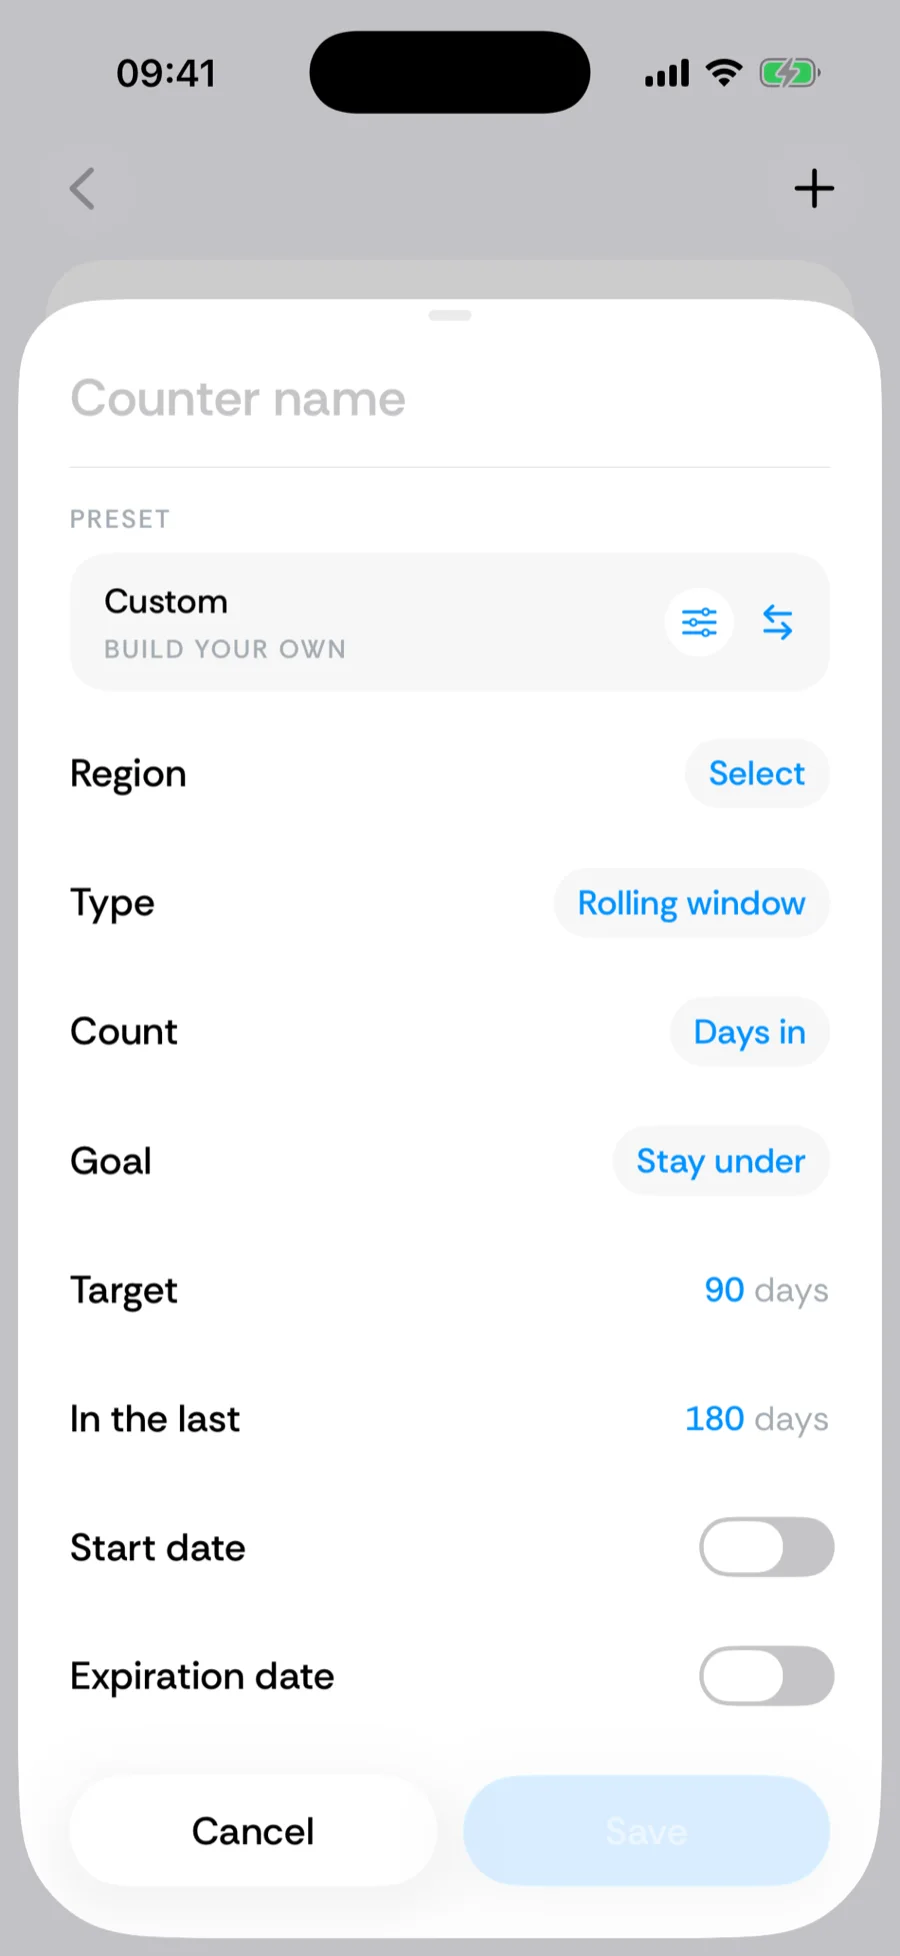
These counters run with the goal Reach at least: the progress bar fills toward the threshold, and crossing it is success rather than a warning — the exact inverse of a stay-under tax counter. Most tax counters can be flipped between the two goals (the weighted US test and Switzerland’s per-stay limit have no goal to flip) in the builder, so the same rule serves both sides of the line. Residency checklists (the Netherlands, Belgium, Japan and Mexico vital-interests counters, Malta and Paraguay) have a Goal of their own, Keep residency or Avoid residency: avoiding it, a Resident verdict turns red and Not resident green. On the vital-interests counters the builder’s footer reads Likely resident or Likely not resident as you answer.
Proving it
Tax authorities granting residency certificates ask for evidence of presence. Export the PDF report — the day-by-day log with data sources reads like the documentation they want, and the country detail screen gives you the same picture in-app.
Related articles
Can’t find what you’re looking for? We answer every message.
Contact support